Fibe Personal Loan App — Instant Loans Up to ₹10 Lakh
Fibe brings your personal loan, credit score check, fixed deposit and mutual fund-backed borrowing into one app. Instead of visiting a branch, filling paper forms or waiting days for a decision, you complete the entire journey — application, KYC, approval and repayment — on your phone. The app is built for salaried professionals who need a straightforward, transparent way to borrow: no hidden charges, no physical paperwork and no need to track a loan across multiple emails or SMS threads. Every step, from the first eligibility check to the final EMI payment, happens inside a single, secure interface.

few minutes


4.6/5
Google play store
568K+ ratingsWhy Use the Fibe Personal Loan App?
The Fibe app handles the entire loan journey on your phone — application, KYC, approval and repayment — with live status updates at every step. No branch visit, no agent call.
Most borrowers come to a loan app because their situation doesn't fit neatly into a bank's standard working hours or documentation checklist. Below is what the app actually does differently, step by step, once you're inside it.

In-app digital KYC
Complete video KYC, DigiLocker and PAN verification directly in the app, no courier of physical documents. Instead of visiting a branch with photocopies of your Aadhaar and PAN, you complete verification through your phone's camera and a short video call-style check. DigiLocker integration pulls your Aadhaar details digitally, so there's no need to manually type in your address or date of birth — it's fetched directly from the government-issued digital document, reducing both the time spent and the chance of a data-entry mismatch that could otherwise delay your application.

Real-time status updates
Push notifications the moment your loan is approved, disbursed, or when an EMI is due. You don't need to open the app repeatedly to check where your application stands. From the moment you submit your details, the app tracks your application through each internal stage — profile review, eligibility assessment, KYC verification, and final disbursal — and notifies you the instant your status changes, so you always know what's happening without guessing.

AI-assisted eligibility check
An automated credit assessment runs once your profile is complete, so you get an offer — or a clear reason you don't qualify — within minutes. Rather than routing every application through a manual underwriter first, the app's automated assessment engine reviews your income, employment and credit bureau data as soon as you submit your profile. This means you're not left waiting days just to find out whether you're even eligible — the initial read on your application happens close to instantly, with the lending partner's final sign-off following once documentation is verified.

Fast EMI payment
Pay via UPI, net banking or debit card without leaving the app. When an EMI is due, you don't need to switch to a separate banking app or website. Payment happens inside the Fibe app itself, through whichever method you find most convenient, and the transaction reflects on your loan dashboard immediately, so your outstanding balance is always current.

Loan dashboard
Track your outstanding balance, payment history and upcoming EMI dates, and download your loan statement anytime. The dashboard is designed to answer the questions borrowers most commonly have without needing to call support: how much do I still owe, when is my next payment due, and what have I paid so far. Your statement is available as a downloadable PDF at any time, which is useful when you need proof of an existing liability for another financial application, such as a home loan or a rental agreement.

In-app support
Raise a query or track a complaint through in-app chat or email support. Support is built into the same app you use for your loan, rather than requiring a separate phone call or a wait in a queue. You can raise a query about a specific transaction, track the status of a complaint you've already logged, or reach out over email — all without needing to leave the app or repeat your account details to a new representative each time.

Part-prepayment, no foreclosure charge
Pay down your loan early from within the app; the surplus goes to your principal, not an exit fee. If your financial situation improves and you want to reduce your loan faster, you can make a part-prepayment directly from the app. Because Fibe charges no foreclosure fee, the full amount you pay goes toward reducing your outstanding principal — which in turn reduces the total interest you'll pay over the remaining tenure, rather than being partially absorbed by an exit charge.

Security
End-to-end encryption, biometric lock and device binding. ISO/IEC 27001 certified and PCI-DSS compliant. Your account is tied to the specific device you register it on, and access can be locked behind your phone's biometric authentication (fingerprint or face unlock), so a lost or stolen phone doesn't automatically mean a compromised account. Data in transit is encrypted end-to-end, and the underlying systems are independently certified against ISO/IEC 27001 (information security management) and PCI-DSS (payment card data security) standards.
In-app digital KYC
Complete video KYC, DigiLocker and PAN verification directly in the app, no courier of physical documents. Instead of visiting a branch with photocopies of your Aadhaar and PAN, you complete verification through your phone's camera and a short video call-style check. DigiLocker integration pulls your Aadhaar details digitally, so there's no need to manually type in your address or date of birth — it's fetched directly from the government-issued digital document, reducing both the time spent and the chance of a data-entry mismatch that could otherwise delay your application.
Real-time status updates
Push notifications the moment your loan is approved, disbursed, or when an EMI is due. You don't need to open the app repeatedly to check where your application stands. From the moment you submit your details, the app tracks your application through each internal stage — profile review, eligibility assessment, KYC verification, and final disbursal — and notifies you the instant your status changes, so you always know what's happening without guessing.
AI-assisted eligibility check
An automated credit assessment runs once your profile is complete, so you get an offer — or a clear reason you don't qualify — within minutes. Rather than routing every application through a manual underwriter first, the app's automated assessment engine reviews your income, employment and credit bureau data as soon as you submit your profile. This means you're not left waiting days just to find out whether you're even eligible — the initial read on your application happens close to instantly, with the lending partner's final sign-off following once documentation is verified.
Fast EMI payment
Pay via UPI, net banking or debit card without leaving the app. When an EMI is due, you don't need to switch to a separate banking app or website. Payment happens inside the Fibe app itself, through whichever method you find most convenient, and the transaction reflects on your loan dashboard immediately, so your outstanding balance is always current.
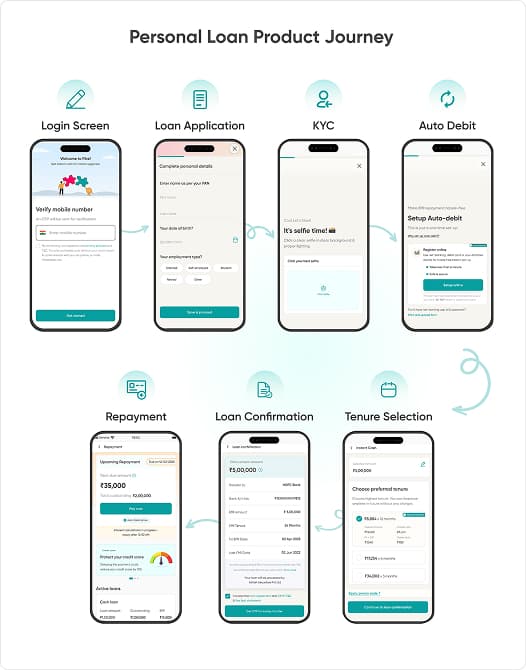
How to Apply for a Personal Loan in 2 Minutes
The entire personal loan application process is on the Fibe app. Approval in 2 minutes. Disbursal to your bank in minutes.
Register securely
Sign up using your mobile number and OTP to securely access your Fibe account and start your online loan application.
Complete your profile
Share a few basic details so we can verify your identity and check your loan eligibility.
Tell us about yourself
Enter your income, employment, address and other required details to help us process your application faster.
Eligibility check
We assess your application using internal policy checks, credit bureau information, income models and other risk indicators. If required, we'll ask you for additional documents.
Digital KYC
Complete your digital KYC through document verification, DigiLocker, Video KYC, bank account validation and other required checks.
Set up repayments
Choose a convenient repayment mandate using UPI, debit card, net banking, Aadhaar or, where applicable, a physical NACH mandate.
Review & receive your loan
Select your approved loan amount and tenure, accept the Key Fact Statement and loan agreement using OTP, and if approved, we'll transfer the funds to your verified bank account.
Is the Fibe Personal Loan App Safe?
A fair question when you're sharing Aadhaar, PAN and bank details with an app. Here's what the app does with your data, why it asks for each permission, and what it doesn't do.
What permissions does the Fibe app request — and why?

Camera
Used for Video KYC verification against your Aadhaar details – required under RBI digital lending norms.
Your camera is not accessed outside of the KYC session

Location (approximate)
Confirms service availability in your area and supports fraud detection.
Not tracked continuously. Not shared with third parties.

Storage (read-only)
Lets you upload a photo of your PAN card or bank statement.
We do not read, copy or transmit your other files

Notifications
Loan status updates, EMI reminders, disbursal confirmations.
You can disable notifications in device settings anytime
SMS (read-only)
Auto-reads OTPs during e-mandate setup.
Only reads OTP-pattern SMS. No message content is stored.
Each of these permissions maps to a specific, functional step in the loan process rather than being requested speculatively. Camera access is only invoked during the KYC step itself; it isn't used to access your phone's camera at any other time. Similarly, SMS read access is scoped narrowly to recognising OTP-format messages during mandate setup – the app is not designed to read or store the content of your other messages.
Security certifications
ISO/IEC 27001 certified · PCI-DSS compliant · FACE member · SOC 2 Certified
ISO/IEC 27001 is an international standard for information security management systems, covering how an organisation identifies, manages and reduces information security risk across its people, processes and technology — not just its software. PCI-DSS compliance specifically covers how payment card data is handled, which is relevant given that EMI payments in the app can be made by debit card. Fibe is also a member of FACE (the Fintech Association for Consumer Empowerment), a self-regulatory body for digital lenders in India focused on responsible lending practices.
Regulatory Context
Fibe's lending partners are RBI-registered NBFCs, and lending through the app is subject to the RBI's Digital Lending Guidelines. You can request deletion of your data by writing to care@fibe.in.
The RBI's Digital Lending Guidelines were introduced to standardise practices across digital lenders — covering areas such as clear, upfront disclosure of the full cost of a loan (through the Key Fact Statement), restrictions on data collection beyond what's necessary for credit assessment, and a defined grievance redressal process for borrowers. Working with RBI-registered NBFC partners means Fibe's loans fall within this regulatory framework rather than outside it.
Is Fibe an RBI-registered lending platform?
Loans are issued by RBI-registered NBFC lending partners, including EarlySalary Services Private Limited (formerly Ashish Securities Private Limited) — the group's primary NBFC arm — alongside its other lending partners:
- EarlySalary Services Private Limited
- Northern Arc Capital Limited
- InCred Financial Services Limited
- HDB Financial Services Limited
- Vivriti Capital Limited
- Kisetsu Saison Finance (India) Private Limited
- Piramal Finance Limited (formerly Piramal Capital & Housing Finance Limited)
- Tata Capital Limited
- Cholamandalam Investment & Finance Company Limited
- Oxyzo Financial Services Limited
- KrazyBee Services Private Limited
- Mirae Asset Financial Services (India) Private Limited
- SMFG India Credit Company Limited
Working with a network of partner NBFCs rather than a single lender means Fibe can continue offering loans even as any individual partner's own lending capacity or risk appetite... Working with a network of partner NBFCs rather than a single lender means... Working with a network of partner NBFCs rather than a single lender means Fibe can continue offering loans even as any... Working with a network of partner NBFCs rather than a single lender means Fibe can continue offering loans even as any individual partner's own lending capacity or...

Fibe App vs Other Personal Loan Apps in India
A factual, point-by-point comparison of the Fibe instant personal loan app against typical instant loan apps and payday cash-advance apps in India.
| What to compare | Fibe Personal Loan App | Typical NBFC Instant Loan Apps | Payday / Cash-Advance Apps |
|---|---|---|---|
| Maximum loan amount | Up to ₹10,00,000 | Often ₹5 lakh or less | ₹5,000 – ₹50,000 typically |
| Repayment tenure | 6 to 36 months (flexible) | 6 to 24 months typically | 7 to 90 days; auto-renews |
| Effective APR | From 18% p.a. (reducing balance) | 18–36% p.a. (varies by app) | Often 100–400% APR effective |
| Interest calculation method | Reducing balance (lower total cost) | Mix of flat and reducing | Flat fee per advance; no EMI |
| Foreclosure / exit charges | Nil | 2%–5% typical | Not applicable (no tenure) |
| Play Store rating | ★4.6 (568K reviews) | ★3.8 – 4.3 (typically) | ★3.5 – 4.0 (typically) |
| Minimum credit score | 650+ preferred; first-time borrowers considered | 650–700 typical cutoff | No credit check in many cases |
| Loan disbursed by | RBI-registered NBFC partner | RBI-registered NBFC / bank | Often unregulated or NBFC |
| Data safety certifications | PCI-DSS + ISO 27001 + SOC 2 Type II | ISO 27001 common; PCI-DSS rare | Often undisclosed |
| App permissions (typical) | Camera, Storage, Location, SMS OTP only | Varies; some request contacts | Often contacts, call logs |
| Hidden fees / rollovers | None. Transparent fee schedule. | Varies; read terms carefully | Common — rollover fees add up quickly |
| Purpose | Planned expenses, emergencies, bridge needs | Planned expenses, emergencies | Short-term salary bridge only |
Can You Apply With a Limited Credit History?
Fibe's eligibility check considers more than your CIBIL score – income stability, employment profile and banking behaviour also factor in.
A single credit score is a snapshot of your past repayment behaviour, but it doesn't always capture your current financial position – someone with a thin credit file because they're early in their career, for instance, may still be a reliable borrower based on how consistently their salary is credited and how they manage their existing bank account. That's the gap the additional factors below are designed to help fill.
What the eligibility check looks at, beyond CIBIL
- Consistent salary credits over recent months
- Employment type and payroll record
- Banking behaviour – overdraft frequency, savings pattern, bounced payments
- The eligibility check involves a hard credit inquiry, which may cause a small, temporary impact to your CIBIL score.
Because the eligibility check involves a hard inquiry rather than a soft one, it's worth applying only when you're genuinely ready to proceed, rather than using the app repeatedly just to 'check' your odds – each hard inquiry is recorded on your credit report and, like any hard inquiry from any lender, can have a small, temporary effect on your score.
Typical eligibility in the app
| Criterion | What to know |
|---|---|
| Age | 19 to 55 years |
| Minimum income | ₹20,000/month in-hand (salaried) or equivalent (self-employed) |
| Employment | Salaried |
| Income proof | Salary slip and bank account statement required |
| Residency | Indian resident with Aadhaar and PAN |
Important note: Loan approval, amount and terms are subject to the lending partner NBFC's credit policy. Eligibility criteria shown here are indicative and don't guarantee approval for any applicant.
Does Checking Eligibility on the App Affect CIBIL?
The eligibility check involves a hard credit inquiry – it is recorded on your CIBIL report and may have a small, temporary effect on your score. Because of this, it is worth applying only when you are genuinely ready to proceed rather than using the app to check your eligibility repeatedly. Like any hard inquiry from any lender, the effect is typically small and temporary.
Important note: Loan approval, amount and terms are subject to the lending partner NBFC's credit policy. Fibe cannot guarantee approval for any applicant. The above criteria are indicative and subject to change.
Loans for Emergencies and Short-Term Cash Needs
Whether it's a medical bill, a rent shortfall, or a gap before payday, the Fibe app processes applications digitally, without a branch visit.
Unplanned expenses rarely arrive at a convenient time. The points below cover what to expect when you're applying for this kind of need specifically, rather than a planned, larger purchase.
Medical and emergency expenses
Applications can be submitted any time; approval and fund transfer timing depend on KYC completion and lending partner approval. Because the application can be started at any hour rather than only during branch working hours, you're not blocked from beginning the process outside a typical 9-to-5 window – though the speed of the final decision still depends on how quickly your KYC documents can be verified and on the lending partner's own approval process.

Short-term cash gaps
Fibe's minimum tenure is 6 months, structured as a regular EMI schedule rather than a single-payment payday advance. Structuring even a short-term need as a 6-month EMI, rather than a single lump-sum repayment, spreads the cost across smaller monthly instalments – which can be easier to manage against a regular salary than a single large repayment at the end of a short period.

Fully digital
Available across 400+ cities.
Because the entire process runs through the app rather than a physical branch network, coverage isn't limited to metro areas alone – applicants in smaller towns and cities within Fibe's operational footprint can apply through the same digital process as someone in a metro.

Income proof required
A salary slip and bank account statement are required as part of the eligibility check. These documents let the lending partner verify both your stated income and your actual banking behaviour, which together inform the eligibility assessment described earlier in this page.

Loan amount
Up to ₹10 lakh, based on your eligibility. The exact amount you're offered depends on your income, credit profile and the lending partner's underwriting policy at the time of application – it's not a fixed amount every applicant receives, and the eligibility check exists specifically to determine what you individually qualify for.

Instant Loan App – Interest Rates and Charges at a Glance
| Fee | Amount |
|---|---|
| Loan amount | Up to ₹10,00,000 |
| Interest rate | Starting from 18% p.a. (reducing balance) |
| Processing fee | Starting from 2% of loan amount + GST |
| Repayment tenure | 6 – 36 months |
| Foreclosure charges | Nil |
| Late payment charge | ₹500 or 3% of the overdue EMI, whichever is higher |
| NACH/e-mandate bounce charge | ₹500 per instance |
| Stamp duty | 0.1% of loan amount |
| Mandate rejection charge | ₹250 + GST |
Illustrative Example
For a loan of ₹5,00,000 over a 36-month tenure at 18% p.a. (reducing balance), with a processing fee of 2% + GST and stamp duty of 0.1%
| Item | Approximate value |
|---|---|
| Loan amount | ₹5,00,000 |
| Tenure | 36 months |
| Interest rate | 18% p.a. (reducing balance) |
| Approximate EMI | ₹18,080/month |
| Approximate total interest over tenure | ₹1,50,880 |
| Processing fee + GST | ₹11,800 |
| Stamp duty | ₹500 |
| NACH/e-mandate bounce charge | ₹500 per instance |
Features You'll Use After Your Loan Is Disbursed
Everything you'd otherwise need to call support to find out is available inside the app.
Here is what the in-app experience looks like after your loan is disbursed.

Loan dashboard
Outstanding balance, next EMI date, amount due, interest paid to date, remaining EMI count.
Everything you'd otherwise need to call support to find out – how much you still owe, when your next payment is due, and how much interest you've paid so far – is visible on a single screen, updated in real time as payments are processed.

Statement download
Download your repayment statement as a PDF, useful for tax filing or rent agreements. A downloadable statement is often required when applying for another loan, filing your taxes, or providing proof of an existing financial commitment to a landlord or another lender – having it available on demand, rather than needing to request it by email, saves a step at a time when you may be under a deadline.

Part-prepayment
See the interest you'd save on a partial early payment before you confirm; no foreclosure charge applies.
Before you commit to a part-prepayment, the app shows you the projected interest saving across your remaining tenure, so you can decide whether the amount you're considering putting toward your loan is better used there or elsewhere.

Fast repayment
Pay via UPI, net banking or card without leaving the app; e-mandate handles automatic monthly debit.
For most borrowers, the e-mandate means EMI payments happen automatically each month without any action required – the manual payment options exist for cases like paying ahead of your due date or making a one-off additional payment outside the regular schedule.

EMI reminders
Push notifications ahead of your due date.
A reminder ahead of your due date is particularly useful if your salary credit date and EMI due date don't line up neatly, giving you a chance to ensure sufficient balance is in your account before the automatic debit is attempted.

Top-up eligibility
The app recalculates your available limit as you repay on time; a top-up offer appears in-app if you qualify.
Rather than needing to submit a fresh application if you need additional funds later, the app automatically re-evaluates your eligibility as your repayment history builds, and surfaces a top-up offer directly on your dashboard if your profile qualifies for one.
App Requirements and Device Compatibility
Before downloading, it's worth confirming your device meets the app's minimum requirements — this avoids starting an application only to find the app won't install or run smoothly partway through.
| Requirement | Android | iOS |
|---|---|---|
| Minimum OS Version | Android 9 (Pie) or above | iOS 15 or above |
| Minimum RAM | 4 GB recommended or above | 2 GB or above |
| Free Storage | Minimum 500 MB free space recommended | Minimum 500 MB free space recommended |
Download the Fibe Personal Loan App
Apply, track and repay your loan entirely from the Fibe instant personal loan app. Available on Android and iOS.
4.6/5
10M+ downloadsRated 4.6 out of 5 from 568K+ ratings
Personal Loan FAQ’s
To get cash immediately through Fibe App, download the app, create an account, complete the application form, upload the required documents, choose your loan amount and repayment term and get instant approval. The funds will be deposited into your bank account within minutes.
Fibe’s Personal Loan App works by allowing users to apply for a personal loan through the app. You can create an account, complete the application form, upload required documents, choose a loan amount and repayment term and get instant approval. The funds are deposited into their account within minutes.
Yes, Fibe’s Personal Loan App is safe. The loan app employs advanced security features, including encryption technologies and two-factor authentication, to protect user data and prevent unauthorized access. User data is stored on secure servers and the app is fully compliant with data protection regulations.
To get a personal loan from Fibe’s Personal Loan App, download the app from the App Store or Google Play, create an account, complete the application form, upload the required documents, choose a loan amount and repayment term and get instant approval. The funds will be deposited into your account within minutes.
There are several loan apps that offer personal loans with instant approval. One of them is Fibe. It allows you to apply for a personal loan and get instant cash with minimal documentation. The funds are usually deposited in your bank account within minutes.
Fibe’s Personal Loan App offers personal loans to salaried individuals who meet the eligibility criteria, including a minimum monthly income requirement.
Fibe’s Personal Loan App offers personal loans with minimal documentation. You only need to upload a few required documents, such as your PAN number, address proof and bank statements, to apply for a loan.
The best app to borrow a personal loan depends on individual needs and preferences. Fibe is one of India’s leading consumer lending apps focused on young and mid-income groups to fulfill their aspirations. It offers you quick cash of up to ₹10 lacs to manage all your financial needs.